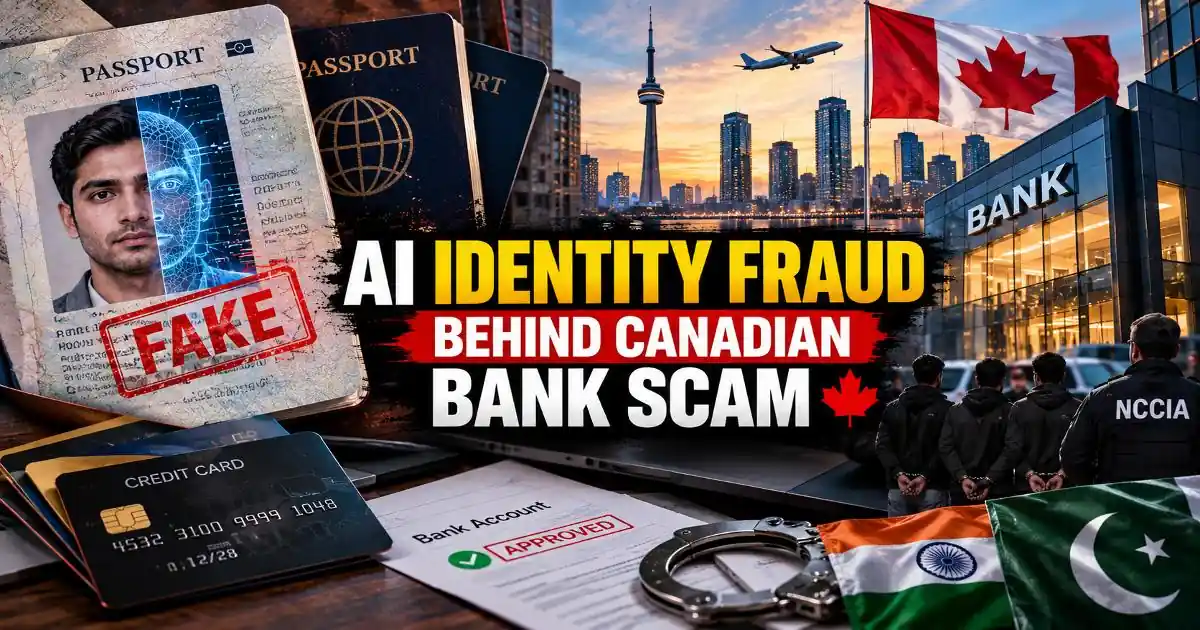
AI identity fraud has become a serious concern for digital banking after Pakistani investigators announced an alleged scheme involving AI-generated passport images, fabricated identities and Canadian credit cards. According to reports published on October 20 and 21, 2026, three suspects in Pakistan allegedly worked with four Indian nationals living in Canada to open bank accounts using false identities and obtain credit cards.
The case was announced by Pakistan's National Cyber Crime Investigation Agency (NCCIA) following arrests in Lahore. Investigators allege that the group combined fabricated identity documents with genuine personal information to make synthetic identities appear legitimate during remote bank account applications. The alleged scheme raises important questions about how financial institutions verify customers when applications are completed entirely online.
Authorities have not publicly identified the Canadian banks involved or disclosed the total alleged financial losses. The investigation is ongoing, and the accusations should not be treated as proof of guilt. Nevertheless, the reported methods illustrate how generative AI, identity verification weaknesses and coordinated online activity can create new challenges for financial security.
What is AI identity fraud?
AI identity fraud occurs when artificial intelligence is used to create or manipulate identity-related material for deceptive purposes. Examples include fabricated passport images, synthetic photographs, altered identity documents and convincing impersonations intended to mislead a verification system.
One related technique is synthetic identity fraud. Instead of stealing the complete identity of an existing person, a fraudster combines real and fabricated information to create an identity that does not genuinely belong to one individual. Some details may be authentic, while the overall identity presented to a bank is false.
This can complicate digital onboarding because different checks may validate different parts of an application. A photograph can appear plausible, a personal detail can match a genuine record, and an uploaded document can look convincing without proving that the applicant is the person they claim to be.
AI-generated material does not automatically pass a bank's security checks. Its effectiveness depends on the verification technology, the documents involved, the information available to the institution and the additional controls applied during account opening.
How the alleged Canadian bank fraud worked
According to reporting based on the NCCIA's statements, the alleged operation involved participants in Pakistan and Canada who performed different roles. Investigators said AI-generated passport images and photographs were used to support applications associated with fabricated identities.
The reported sequence began with the preparation of identity material. The Canada-based suspects allegedly supplied fabricated passport images and photographs to their Pakistan-based associates. Investigators said the group combined these materials with genuine personal details, including identity numbers and dates of birth, to construct synthetic identities.
The Pakistan-based suspects allegedly used the information to apply remotely for accounts at Canadian banks. Reports also named Dolphin Anty, an anti-detect browser designed to alter or mask browser and device characteristics, as a tool allegedly used during the process. Its reported presence does not establish that the software itself is inherently malicious; such tools can have legitimate uses, although concealing identity or device information can also be abused.
According to investigators, credit cards were subsequently issued and delivered to the Canada-based participants. The cards were allegedly used up to their credit limits before being discarded. Banks reportedly identified irregularities while investigating the resulting losses.
These details come from the investigators' account as reported by news organizations. The precise bank onboarding controls involved, the full amount of the alleged losses and the status of all seven suspects have not been independently established in public reporting.
Why AI-generated passports create a verification challenge
Remote account opening depends on a series of checks that may include document validation, facial comparison, identity database searches, address verification and risk assessment. These checks serve different purposes and should not be treated as interchangeable.
A document image may look realistic without being authentic. Similarly, a facial comparison may indicate that two images resemble each other without establishing that either image belongs to a real, verified identity. A convincing image is evidence to examine, not proof of identity.
More robust systems combine multiple independent signals. Depending on the jurisdiction and available services, a financial institution may validate document security features, check information against trusted records, verify that a customer is physically present through appropriate liveness checks, and compare information across the application.
Even these methods have limitations. Automated checks can produce false positives and false negatives, while genuine customers may encounter difficulties because of lighting, camera quality, accessibility needs or inconsistent records. Effective verification must balance fraud prevention with privacy, accessibility and fair treatment.
The central lesson is that AI-generated identity material should not be assessed solely by how realistic it looks. Banks need to establish whether the document is genuine, whether its information belongs to the applicant and whether the applicant is entitled to use that identity.
The role of browser masking and digital identity signals
Online financial services may assess technical information alongside documents and personal details. These signals can include device characteristics, session patterns, network information and inconsistencies between an applicant's claimed circumstances and the application environment.
Anti-detect browsers can modify some browser fingerprint information. Such software is not proof of criminal activity by itself, because privacy, testing and account-management workflows may use browser isolation or profile separation. However, unexplained inconsistencies can become relevant when combined with questionable documents or other suspicious application patterns.
Financial institutions should avoid relying on a single signal to make a high-impact decision. An unfamiliar device or masked browser fingerprint does not establish fraud, just as a familiar device does not establish that an application is legitimate.
Instead, banks can combine risk-based checks, identity verification, transaction monitoring and manual review when necessary. Suspicious applications may require additional evidence or a more reliable verification method before credit is issued.
How banks can strengthen digital identity security
Financial institutions can reduce exposure by treating identity verification as a layered process rather than a single photograph or document upload. The appropriate controls depend on local regulations, available identity infrastructure and the risks associated with each product.
- Validate documents against trusted sources. Where supported, verify passports and other identity documents through authoritative systems rather than relying only on uploaded images.
- Use appropriate liveness checks. Confirm that the applicant is genuinely present when required, while recognizing that no single facial or liveness technology detects every form of impersonation.
- Cross-check identity attributes. Look for inconsistencies among names, dates of birth, identity numbers, addresses and other relevant records. A collection of individually plausible details may still describe a fabricated identity.
- Assess suspicious application patterns. Identify repeated attempts, unusual device signals, linked applications and inconsistent account details. Apply proportionate checks rather than treating one anomaly as conclusive evidence.
- Strengthen credit issuance controls. Use appropriate limits, additional review and transaction monitoring for applications that present elevated risk, particularly before extending substantial credit.
- Monitor accounts after approval. Detect unusual spending, suspicious account changes and rapid credit utilization. Identity checks at account opening should be supported by ongoing fraud monitoring.
These controls should operate within applicable privacy and financial regulations. Banks also need secure data handling, restricted employee access and clear procedures for investigating suspicious applications without unfairly excluding legitimate customers.
What ordinary customers should know
The reported case primarily concerns alleged fraud against financial institutions, not a claim that every Canadian banking customer has had their identity stolen. Customers do not need to assume their accounts are compromised simply because AI-generated documents were allegedly used in a separate investigation.
However, anyone applying for a bank account or credit card should protect their personal information. Submit identity documents only through official banking channels, verify website addresses before uploading sensitive material, and avoid sending passport scans or identity numbers through unsolicited messages.
Use unique passwords and multifactor authentication wherever available. Review account activity and transaction alerts, and contact the bank promptly if you notice unfamiliar applications, credit inquiries or transactions. If you believe your identity information has been misused, ask the relevant institution how to report the incident and secure your accounts.
Businesses should also train employees to recognize suspicious identity documents and establish clear escalation procedures. Security teams can use AI-based detection tools, but the results should be evaluated alongside reliable evidence and human review.
What this case reveals about the future of AI security
Generative AI makes it easier to create realistic-looking digital content, but the underlying problem is broader than image generation. Fraud becomes more difficult to detect when fabricated documents are combined with genuine information, remote applications and tools that obscure technical signals.
The response cannot depend on detecting whether an image simply looks AI-generated. Detection tools can help, but they may become less reliable as generation methods improve. Verification systems need to establish authenticity and identity through trustworthy evidence, multiple checks and ongoing monitoring.
The case also demonstrates why international cooperation matters. When participants, digital infrastructure, financial institutions and evidence are spread across multiple jurisdictions, investigations may require coordination between law enforcement agencies and private organizations.
For developers and businesses building online services, the practical lesson is to design identity verification around the threat model rather than assuming that a polished photograph or uploaded document is sufficient. For customers, careful handling of personal information and prompt reporting of suspicious activity remain useful protections.
AI can help organizations improve fraud detection, but it can also be misused to manufacture convincing false identities. Strong digital security depends on verifying the person behind the application, protecting sensitive information and responding quickly when multiple warning signs appear.
Official References & Citations
- "AI Identity Fraud: How Fake Passports Allegedly Fooled Canadian Banks Intelligence Briefing" — Softech Alert Security Intelligence
- "Cyber Threat & Scam Analysis Report" — Digital Defense Portal
- "Consumer Advisory on Web & Mobile Threats" — Security Guidelines